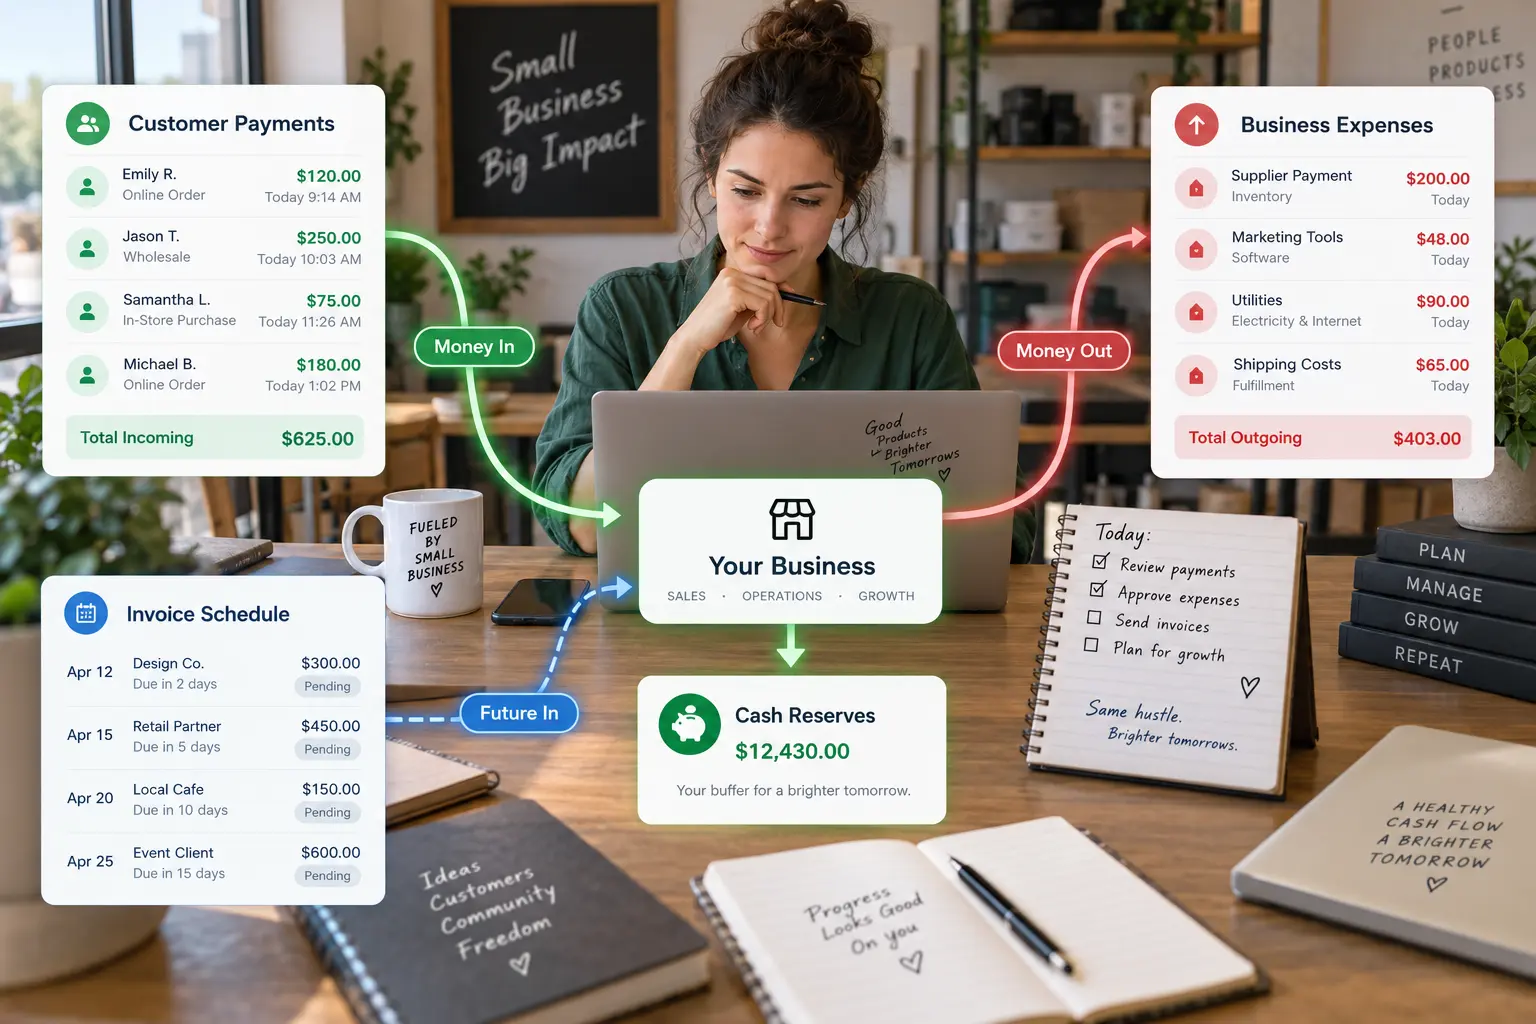
To improve small business cash flow, owners need to manage both sides of the cash cycle: how quickly money comes into the company and when money leaves it. Practical steps include invoicing promptly, following up on receivables, forecasting upcoming cash needs, reviewing recurring expenses, managing inventory carefully, and maintaining an appropriate cash reserve.
The goal is not simply to increase sales. A company can generate substantial revenue and still experience cash shortages when customers pay slowly or major expenses become due before incoming payments arrive.
Start With a Simple Cash Flow Forecast
Improving cash flow begins with understanding when money is expected to enter and leave the business.
A cash flow forecast estimates future inflows and outflows over a selected period. It can include expected customer payments, rent, payroll, supplier invoices, loan payments, taxes, software subscriptions, inventory purchases, and other predictable transactions.
The forecast does not need to predict every amount perfectly to be useful.
Its main purpose is to identify periods when available cash may become tight. If an owner can see a potential shortfall several weeks ahead, there is more time to adjust spending, accelerate collections, discuss supplier terms, or evaluate financing options.
Invoice Customers Promptly
A completed sale does not improve available cash until the company receives payment.
For businesses that invoice customers, delays in sending invoices can unnecessarily extend the collection cycle.
Invoices should be issued promptly and contain clear information about the amount due, payment methods, applicable payment terms, and other relevant details.
Businesses should also maintain a simple process for tracking whether invoices have been paid.
An invoice that remains unnoticed after its due date can create avoidable pressure on cash flow.
Monitor Accounts Receivable
Accounts receivable represents qualifying amounts customers owe the business.
A growing receivables balance may indicate strong sales, but it can also mean that a larger portion of the company’s revenue has not yet turned into usable cash.
Review outstanding invoices regularly.
Owners can identify overdue accounts, send appropriate reminders, correct billing problems, and investigate invoices that customers may be disputing.
Consistent follow-up is generally more effective than allowing unpaid invoices to accumulate for months.
Make Payment Terms Clear
Customers should understand when payment is expected before a transaction becomes overdue.
Clear payment terms can reduce confusion and help businesses plan incoming cash more accurately.
The appropriate terms depend on the company’s industry, customers, contracts, and competitive environment.
Some businesses require payment immediately. Others use deposits, milestone payments, or invoicing terms that allow customers additional time.
For larger projects, a payment structure tied to project stages may help reduce the amount of work performed before any cash is received.
The important point is to choose terms deliberately rather than allowing payment timing to develop without a clear policy.
Review Expenses Without Cutting Essential Capacity
Reducing unnecessary spending can improve cash flow, but indiscriminate cost cutting can create new problems.
Start by reviewing recurring expenses.
Software subscriptions, unused services, duplicate tools, excessive storage, unnecessary fees, and outdated vendor arrangements are examples of areas worth examining.
However, an expense should not be eliminated solely because it costs money. A tool, employee, supplier, or service that supports revenue or essential operations may provide significant value.
The better question is whether each recurring cost still contributes enough to justify the cash it consumes.
Owners researching finance, budgeting, banking, credit, and everyday business management can also use GrowBizLab for practical advice while building a broader understanding of small-business financial decisions.
Manage Inventory With Cash Flow in Mind
Inventory ties up cash until products are sold and customers pay.
Too little inventory can cause missed sales, while too much can leave substantial money sitting in products that move slowly.
Businesses that carry inventory should monitor which products sell consistently, which items remain unsold, and how long stock is typically held.
Purchasing decisions can then reflect realistic demand rather than assumptions.
This does not mean minimizing inventory at all costs. Instead, businesses should balance product availability against the amount of cash committed to stock.
Examine the Timing of Supplier Payments
Cash flow management involves payment timing as well as payment amounts.
Businesses should understand supplier terms and plan payments accordingly.
Paying obligations on time is important, but paying substantially earlier than required may reduce available cash sooner than necessary unless an early-payment benefit justifies doing so.
Where appropriate, businesses may also discuss payment arrangements with suppliers. The availability and suitability of different terms will depend on the commercial relationship and circumstances.
The objective is to coordinate outgoing payments with expected cash inflows without ignoring contractual obligations.
Build a Practical Cash Reserve
Unexpected costs are part of running a business.
Equipment can fail, customers can pay later than expected, seasonal demand can change, or an unplanned expense can arise.
A cash reserve can provide additional flexibility during these periods.
There is no universal reserve amount that fits every company. The appropriate level depends on factors such as fixed expenses, revenue stability, payment cycles, access to financing, seasonality, and overall risk.
Businesses can build reserves gradually rather than treating them as an all-or-nothing goal.
Be Careful When Using Financing to Solve Cash Problems
Financing can sometimes help a business manage timing gaps or fund productive opportunities, but borrowed money does not automatically fix weak cash flow.
A loan or line of credit creates cash initially, yet repayment obligations can increase future cash outflows.
Before borrowing, owners should understand why the cash shortage exists.
A temporary timing gap caused by receivables may be different from an ongoing situation where normal business activities consistently consume more cash than they generate.
Financing decisions should therefore be considered alongside profitability, repayment capacity, and expected future cash flows.
Review Cash Flow Regularly
Cash flow management works best as an ongoing process.
Owners can periodically compare expected cash movements with what actually occurred. Unexpected differences may reveal late-paying customers, rising costs, inaccurate forecasts, unusual purchases, or changing sales patterns.
This information makes future forecasts more useful.
Regular reviews also help owners distinguish temporary cash timing issues from deeper financial problems.
Improving small business cash flow ultimately requires coordination between collections, expenses, payment timing, inventory, reserves, and financial planning. When owners understand where cash is coming from, where it is going, and when those movements will occur, they can make operational decisions with a clearer view of the company’s short-term financial position.